Your Local Mortgage Lender
Located in Tampa, Florida
Personalized Mortgage Experience
Moses Alford offers personalized service and loan options you'll love. We shop multiple lenders to find the best rate and product for you, getting you into your dream home faster.
With wholesale interest rates and cutting-edge technology, we make the mortgage process seamless. Trust the experts who focus solely on mortgages. Support your local community and experience elite client service.
Let us help you achieve your homeownership dreams!
The Home Loan Process
Mortgage Pre-Approval
Get pre-approved from one of our Loan Officers to see how much you can afford.
House Shopping
Work with a trusted Real Estate Agent to find a home you would like to move into.
Loan Application
Complete your home loan application to get the lending process started.
Don't take my word for it
Mortgage Programs
Experience the best mortgage experience located in Tampa, Florida.
Home Loan Options
Our experienced mortgage advisors will walk you through the best mortgage loan program that will fit your specific scenario.
Conventional Home Loans.
FHA Home Loans.
USDA Home Loans.
VA Home Loans.
Frequently Asked Questions
How often can I refinance my mortgage?
There is no limit to the number of times you can refinance. However, you must qualify every time you apply and there will be costs associated with closing the loan each time.
Can I buy a home if I do not have money for a down payment?
Yes! There are a number of bond programs that offer low or no down payment financing options.
How do I know which mortgage is right for me?
The key to choosing the right mortgage is to understand the range of options and features available to you, as well as your budget, circumstances, and goals. Our licensed mortgage professionals are here to help you navigate that process. The more you know, the more comfortable and confident you will be choosing the best option for you and your family.
How long will the loan process take?
The Truth in Lending Act (TILA) does not permit a lender to close a loan until at least seven (7) business days have passed from the date your application was received. A typical home loan takes 30 days, as a number of third-party services such as appraisals, title work, and credit are required in conjunction with the mortgage process. Once you familiarize your Loan Officer with the details of your specific loan scenario, they will be able to provide you with a more specific timeline.
Will I qualify for a home loan?
The only way to find out is to speak with a qualified mortgage professional. Our Loan Officers have helped numerous clients who didn’t know if they could qualify to become home owners. We take the time to understand your financial situation and long-term financial goals, and then match you with the loan program that best fits your needs. Your approval for a loan may also largely depend on the price of the home you are financing. Getting pre-qualified prior to beginning your home search can give you an idea of what you may be able to afford.
Why do people refinance their mortgages?
Homeowners typically refinance to save money, either by obtaining a lower interest rate or by reducing the term of their loan. Refinancing is also a way to convert an adjustable loan to a fixed loan or to consolidate debts.
How much money will I have to pay upfront to buy a home?
This question does not have a simple, one-size-fits-all answer. The exact amount will depend on the price of the home you buy as well the type of mortgage financing you choose. Depending on your loan program, your down payment could be as much as 20% of the home’s price or as little as 3%, while some loans require no down payment at all.
Can I get a mortgage after bankruptcy?
You may still qualify for a home loan even if you have experienced a bankruptcy. The best way to find out if you qualify is to talk with a Loan Officer to discuss your options. Be sure to bring all paperwork regarding your bankruptcy so your Loan Officer can find the program that best fits your situation.
Should I lock my interest rate now, or wait until we are closer to our closing?
Interest rates fluctuate all day, every day. If an interest rate is good, it may be in your best interest to lock now. If you wait, you run the risk of an increase in rates later. If you are concerned that rates may go down after you lock, contact your Loan Officer to discuss your options. Some programs allow you to lock for an extended period and choose to lower your rate should a better one become available.
Most Recent Blog Updates
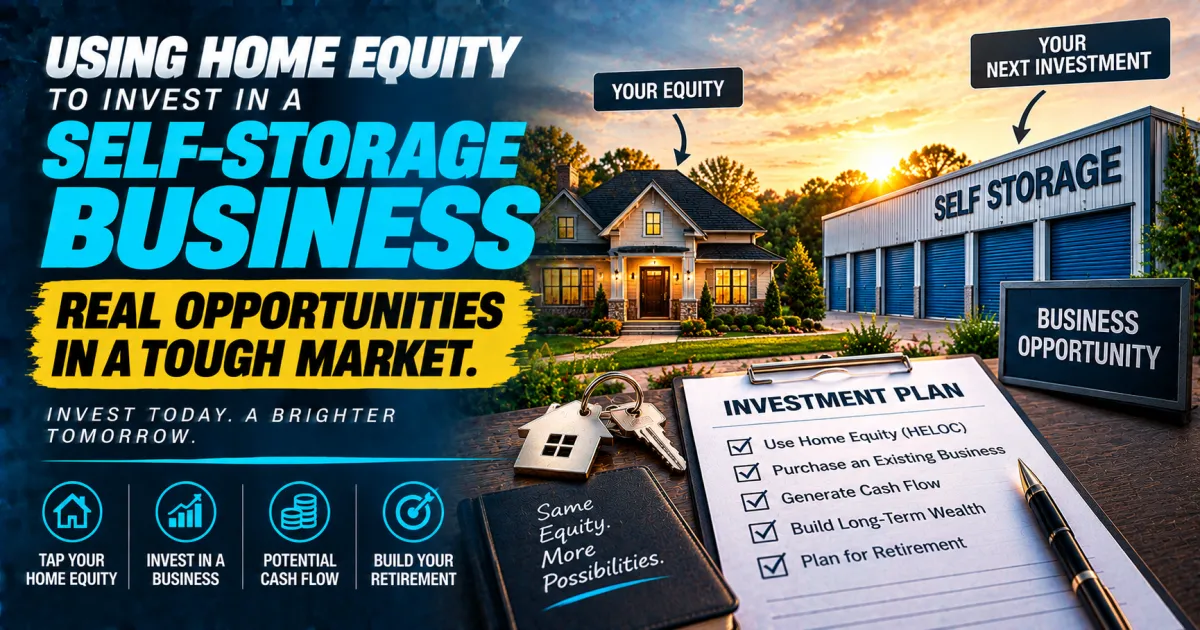
A Florida Homeowner Used a HELOC to Buy a Self Storage Business and Here Is How the Strategy Worked
The Real Deal That Shows What Equity and a Slower Market Can Do Together
Moses Alford just helped a client in North Florida do something that more homeowners with significant equity should at least know is possible. It is not a complicated concept but it requires someone who can see the opportunity in a situation that most people would overlook.
The Client, the Goal, and the Opportunity
The client has been on the same job for years. He owns his home free and clear with no mortgage. His goal is to put himself in a position to retire within the next ten years. That combination of job stability, debt-free homeownership, and a clear long-term financial objective is a strong foundation for a strategic move.
He found an operating self-storage business that had been sitting on the market for a while. That detail matters. A business that has been sitting means fewer competing buyers and fewer competing buyers means meaningful negotiating leverage. He used that leverage to negotiate a significant discount off the asking price before any financing was even discussed.
How the Financing Came Together
The equity sitting in his free-and-clear home was the capital source. Moses helped him access that equity through a HELOC to help finance the purchase. The home that had been holding a large amount of idle equity became the foundation for acquiring an income-producing asset.
He is now buying an existing business that is already operational and positioned to generate cash flow from day one. Not a startup. Not a concept. An operating business with existing customers, existing revenue, and existing infrastructure. And because he negotiated a discount before closing the entry point is better than the asking price suggested it would be.
Why This Matters for the Retirement Goal
A business that cash flows from day one and grows over the next decade is a fundamentally different retirement asset than a savings account or a stock portfolio. It is something he has some control over. Something he can build. Something that potentially compounds in value alongside the cash flow it generates.
The self-storage sector specifically is considered by many business investors to be one of the more recession-resistant operating business models. Lower operating costs relative to revenue, consistent demand, and scalable management structures make it a common target for buyers who want an operating business rather than a passive investment.
The Broader Point Worth Taking Away
A tough market does not mean there are no opportunities. Sometimes a tough market is exactly what creates them. Fewer buyers in a market means more leverage for the buyers who are positioned and ready to move. A business or investment property that has been sitting gives a prepared buyer room to negotiate that simply does not exist when multiple offers are stacking up.
If you have significant equity in your home and you have been thinking about buying a business or another investment Moses Alford wants to run the numbers with you. HELOC, cash-out refinance, or another structure depending on the situation. You bring the opportunity and he will help figure out how to finance it.
Sources
ConsumerFinancialProtectionBureau.gov
FannieMae.com
MortgageNewsDaily.com
SBAGov
Investopedia.com

Mortgage Calculator
See your total mortgage payments using the tool below.
| Year | Interest | Principal | Balance |
|---|